

I became interested in GE Healthcare after reading an article about it from Guardian Research, and I really like its hardware-plus-SaaS business model. GEHC has underperformed its GE brethren since the spinoffs in 2023-24, but GEHC’s value unlock seems to be merely delayed, rather than dead. Finally, I believe GEHC is making the world a better place (I know that sounds cliché, but I think it’s true) by spearheading real-life AI applications for patient diagnostics.
A Brief History
GE Healthcare got its start in 1893 under the name Victor Electric Company when Charles Samms and Julius Wantz started a six-man operation to supply the dental industry with certain equipment. Victor Electric quickly pivoted to X-ray machines, where it had runaway success. In 1913, a researcher developed the hot-cathode, high-vacuum X-ray tube used in Victor’s early machines. In 1920, GE acquired Victor Electric (renamed GE X-ray), marking the start of its century-long foray into medical machines.
During World War II, GE X-ray saw rapid growth because its machines were deployed to the front lines to help injured soldiers. In 1964, GE X-ray began developing patient care systems like the continuous cardiac monitor, moving beyond imaging into broader clinical technology. In the 1970’s, GE commercialised the CT scanner, becoming a pioneer in computed tomography. In 1982, GE X-ray invented the MRI scanner, further improving diagnostic accuracy and establishing GE as a dominant player in magnetic resonance imaging. In 1994, GE X-ray was formally incorporated as a GE subsidiary, receiving the name GE Healthcare.
In 1998, GE Healthcare acquired Marquette Medical Systems, expanding its diagnostic cardiology and patient monitoring product suite. During the first days of the 21st century, GE Healthcare introduced full-field digital mammography, a major advancement in women’s cancer screening. In 2004, GE Healthcare acquired Amersham plc to expand its reach into radiopharmaceuticals. In 2008, GE Healthcare created the Vscan, an ultrasound device that fits in your pocket, showcasing GE’s push for more accessible imaging for clinicians. In 2011, GE Healthcare released the Revolution CT scanner, pushing the frontier of computed tomography even farther.
In 2014, GE Healthcare launched Predix, its industrial analytics platform, signaling the company’s foray into digital healthcare solutions and data-driven diagnostics. In 2019, GE Healthcare received FDA approval for deep learning-based CT image reconstruction, one of the first AI authorisations in medical imaging.
On January 4th 2023, GE Healthcare was officially spun out from General Electric under the ticker GEHC, with Peter Arduini becoming CEO. On March 18th 2026, GEHC completed the acquisition of Intelerad for $2.3 billion, representing a strategic pivot toward AI-centric diagnostics and high-margin SaaS.
Business Model
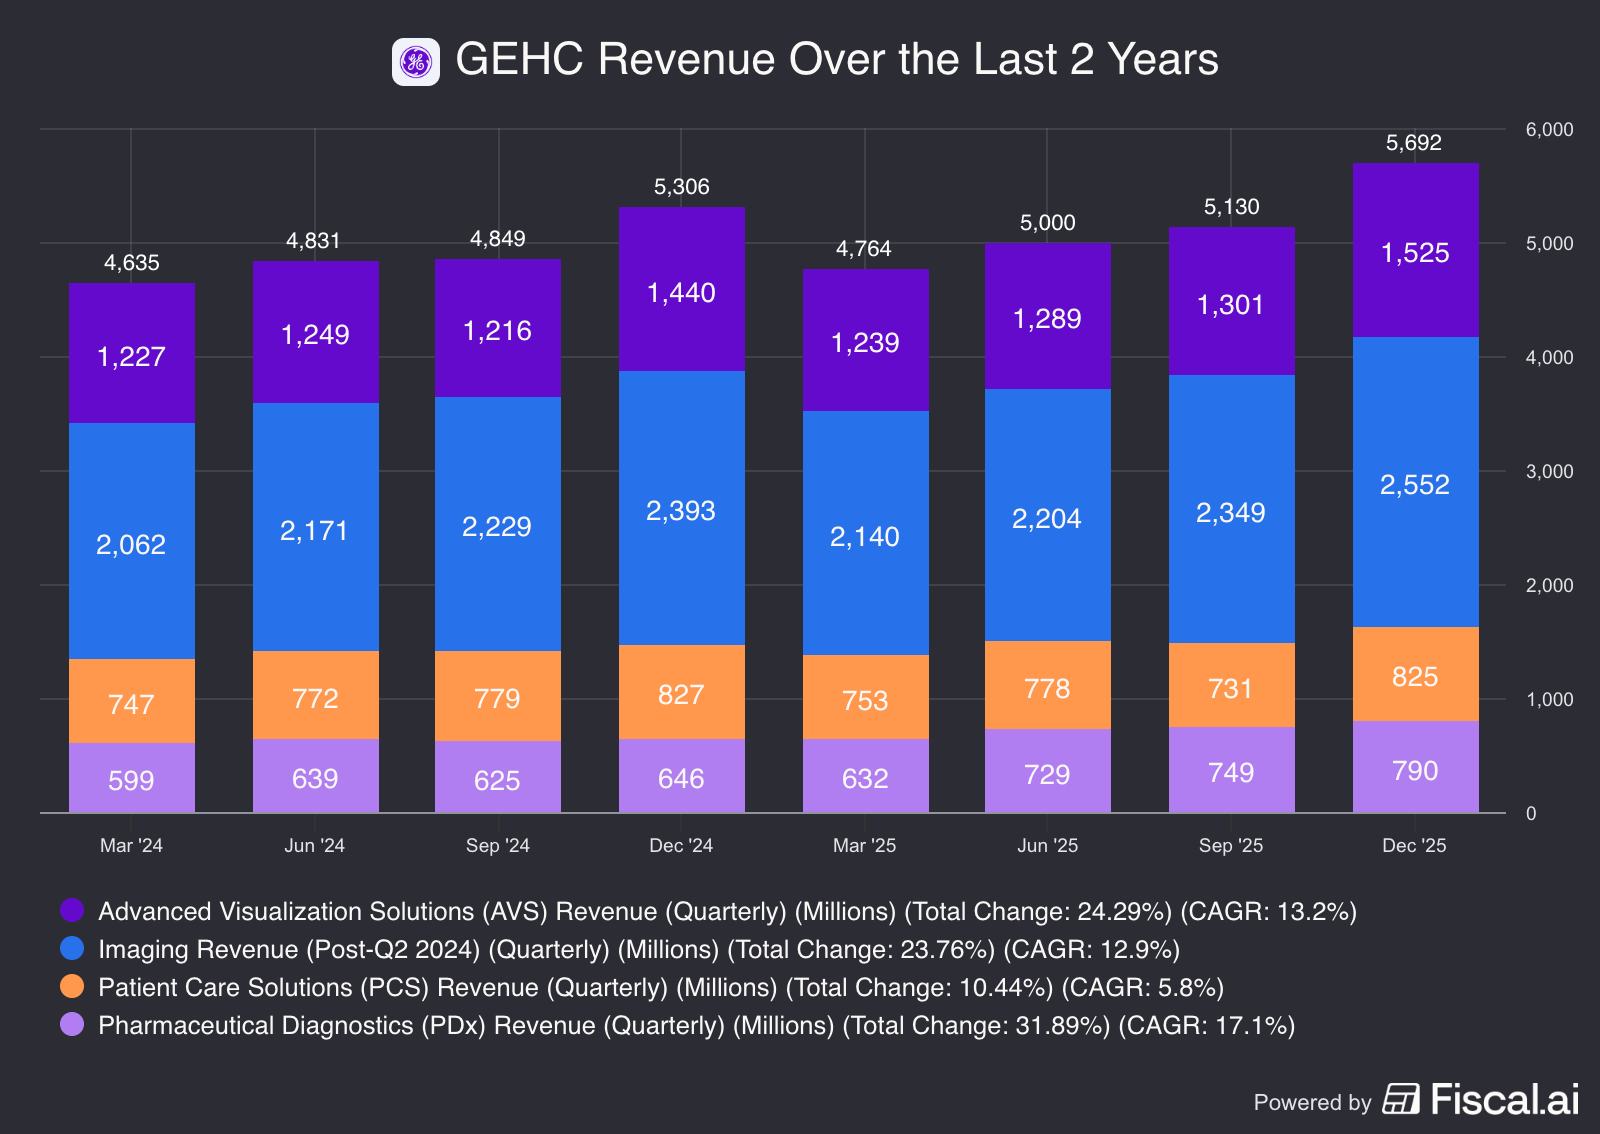
Imaging is the backbone of GEHC’s revenue. It accounts for roughly 46% of revenue and is growing at 4.4% year-over-year. This segment spans Molecular Imaging (MI), Computed Tomography (CT), Magnetic Resonance (MR), Women’s Health, and X-ray. This supports oncology, cardiology, neurology, nuclear medicine, and orthopedics. The model of this segment combines the sale of MRI, CT, and X-ray machines with software-as-a-service. However, margins are not great (12% EBIT margins), reflecting capital intensity and competition.
GEHC’s second-largest segment is Advanced Visualization Solutions, making up a quarter of revenue. This segment was restructured in mid-2024 and now serves customers through Specialized Ultrasound and Procedural Guidance care. It offers comprehensive women’s care. EBIT margins are 26%, and revenue is increasing by 4.4% year-over-year.
Patient Care Solutions accounts for about 15% of revenue and includes GEHC’s expansive bedside care systems, such as monitors, ventilators, anesthesia machines, and infant care equipment. EBIT margins are similar to those of Imaging, at around 12%, and revenue declined 1.25% y/y.
Pharmaceutical Diagnostics is GEHC’s smallest segment, but the best segment. It only accounts for 14% of revenue. This segment supplies contrast and radiopharmaceutical imaging agents to the radiology and nuclear medicine industries. Contrast agents are substances injected into a patient before a CT or MRI scan that help certain parts of the body show up better on the image. Radiopharmaceutical agents are a little different. These are radioactive compounds designed to travel to a specific target in the body and emit detectable radiation. Then, a scanner (usually a PET or SPECT machine) picks up where the agent accumulated, allowing clinicians to see how an organ is behaving rather than just looking at it, which is what contrast agents do. This is the most promising segment and the fastest growing, at 22% year-over-year.
GEHC has two streams of revenue: selling tangible products and selling services through its SaaS platforms. Real-world products are 66% of revenue, and services are the remaining 34%. Management is trying to flip this, setting a goal of having 60% derived from services over time.
Products revenue is currently $13.7 billion. This revenue comes from selling the actual machines, like a CT scanner or an MRI machine. This portion of revenue currently has $5 billion in remaining performance obligations (backlog). This is basically guaranteed revenue that will be flowing in over time.
Now let’s dive into the software side of the business. Services has total remaining performance obligations of $10.7 billion, which is great, as management has said they are focusing on making Services revenue a more significant portion of revenue, which will flow through to the bottom line and uplift margins. I will break down each software GEHC sells, and these businesses will appear in order of most revenue to least.
Centricity is GEHC’s legacy software empire, and despite its age, it generates the purest software revenue in the portfolio. It is a sprawling collection: Centricity RIS (radiology scheduling and reporting), Centricity PACS (image archiving), Centricity Cardio Enterprise (cardiac workflows), Centricity Business (revenue cycle management), and Centricity High Acuity (ICU and anesthesia). The key dynamic here is switching costs because hospital IT systems don’t get replaced unless something goes catastrophically wrong. Thousands of facilities around the world have been running Centricity for decades, paying annual maintenance and support contracts that recur as reliably as any SaaS subscription.
Intelerad has a disclosed ~$270M annual revenue run rate, with roughly 90% of that being recurring, an unusually clean and high-quality revenue stream, spread across more than 1,500 international healthcare organizations. The acquisition, which closed in March 2026 for $2.3 billion, gives GEHC access to Intelerad's cloud-native Picture Archiving and Communication System (PACS), workflow orchestration tools, and image sharing software, and is specifically designed to accelerate GEHC's shift toward a SaaS model. The deal was struck at roughly a 10x revenue multiple, which signals how much management values recurring software revenue relative to hardware.
Edison Datalogue holds the #1 spot in Vendor Neutral Archive (VNA)globally, a strong signal of meaningful revenue, since VNA is mission-critical infrastructure for large health systems. Think of a VNA as the universal image warehouse: it stores and routes medical images regardless of which scanner or software created them. Once a hospital standardizes on one, they rarely leave.
Command Center operates differently — it sells large enterprise software deals to health systems as an operational orchestration layer, using real-time electronic medical record data and AI to surface care bottlenecks. The deal sizes are large, but the customer count is smaller than that of Centricity.
Edison True PACS is effectively the modern replacement for the aging Centricity PACS, and its revenue will grow as the legacy base migrates. However, it's still in transition as of this moment.
MIM Software, acquired early in 2024, brought a respected niche platform for nuclear medicine dose management and oncology treatment planning — high value per customer, but a narrow addressable market. Imaging Insights and CardioVisio are subscription analytics products layered on top of existing hardware relationships, generating meaningful but secondary revenue.
Edison Digital Health Platform, AIR Recon DL, and Critical Care Suite represent GEHC's most important strategic bets but are the least mature in terms of standalone monetization. GEHC's stated goal is to triple its cloud-based solutions and grow digital revenue by around 50% by enabling a subscription-based model, and these platforms are where that growth is supposed to come from. AIR Recon DL is particularly interesting: it's GE's deep-learning MRI reconstruction AI, and the company is beginning to sell it as a software subscription add-on rather than bundling it for free with scanners.
There is a bit of a ticking time bomb for GEHC because it needs to migrate legacy software revenue (like Centricity) onto modern, cloud-native platforms (Edison, Intelerad) before that revenue erodes. The Intelerad acquisition is the clearest statement yet that management understands this urgency — analysts described it as a "strategic shift" from a capital-expenditure-heavy imaging hardware business to a high-margin, recurring SaaS-led diagnostic platform, creating a cloud-first ecosystem that unifies hospital, ambulatory, and teleradiology workflows. The hardware business funds the transition; the software business determines the valuation multiple the market assigns to it.
Industry
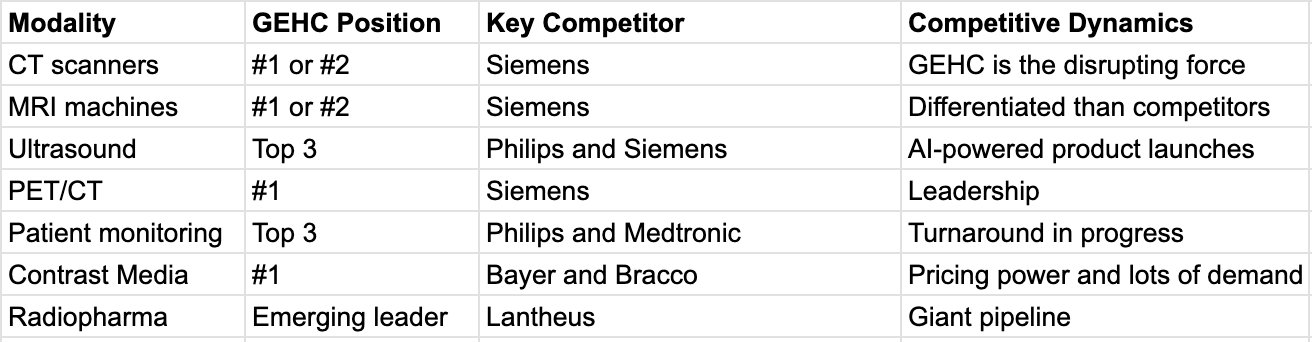
GEHC is part of the healthcare machines industry. This industry has massive barriers to entry because of the regulations in place to ensure machines are of high quality, resulting in only a few large players. GEHC’s two main competitors are Siemens Healthineers (ticker: SMMN.Y) and Koninklijke Philips (ticker: PHG).
Siemens is the largest of the three by revenue. Siemens has Imaging (similar to GEHC) and Diagnostics. Siemens also acquired Varian in 2021, making it a key differentiator from its competitors. Varian provides Siemens with unique exposure to radiotherapy and cancer care. Siemens also recently acquired Novartis’ radiopharmaceuticals division to compete with GEHC’s PDx.
Philips has had a rocky last couple of years. In 2024, Philips settled Respironics’ personal injury litigation in the United States, costing $1.1 billion. This also triggered a massive recall of ventilators that sucked up all of management’s attention and caused margins to deteriorate below Siemens’ and GEHC’s.
This industry has been in a mature growth phase for a while, but that is quickly changing. Since the dawn of artificial intelligence, AI-native software startups have sprung up to compete with GEHC’s software. These software companies are lighter because they don’t sell hardware and can integrate directly into the hospital’s workflow. However, this narrative disregards the GEHC thesis: GEHC can package its software with its machines, having the machines sell the software. GEHC is also facing competition from Chinese players who are using lower prices to drive adoption in emerging markets, which GEHC has acknowledged and is trying to compete with.
Management
The current CEO of GEHC is Peter Arduini. Arduini has spent his entire career in the medical technology and healthcare industry. He originally cut his teeth at GEHC as a regional sales manager early in his career, before leaving and eventually being wooed back decades later to lead the company's high-stakes spin-off from General Electric before returning to GE. He served as President and CEO of Integra LifeSciences from January 2012 to December 2021, and before that was Corporate Vice President and President of Medication Delivery at Baxter Healthcare from 2005 to 2010. Before Baxter, he spent 15 years at GE Healthcare in a variety of management roles, culminating in leading the global functional imaging business. Early in his career, he spent four years with Procter & Gamble in sales and marketing before moving into the medical technology world.
94% of Arduini’s yearly salary is stock-based, meaning he is heavily incentivized to outperform expectations and grow the business. Only 35% of his net worth is tied to his GEHC stock, which isn’t great, but it is still substantial. Overall, I like his vision and drive.
Capital Allocation
GEHC uses M&A selectively to enter or expand in high-growth areas, rather than for large-scale consolidation. A recent example: the closing of their acquisition of Nihon Medi-Physics, which they expect will increase global access to their next-generation radiopharmaceuticals. The M&A approach is described as disciplined, meaning they're not pursuing deals for scale alone, but for strategic fit in precision care and digital health. This is the majority of their capital allocation strategy, but they also have a 0.2% dividend yield. This represents about 3.1% of free cash flow, so I would definitely like to see this grow over time.
Tailwinds and Growth Drivers
GEHC is most interesting to me because of the tailwinds that will power the stock over the next twenty years.
First, the world is aging fast. The United Nations projects that the population aged 65 and above will double over the next 30 years, reaching 1.6 billion by 2050. In the US specifically, IBISWorld’s 2025 medical device industry report highlights that adults aged 65 and older (this demographic is most likely to use GEHC machines) are expected to outnumber children by 2034. That is a watershed moment for healthcare demand, and it is less than a decade away. Aging populations drive exponential increases in chronic disease prevalence across cardiovascular disease, cancer, neurological disorders, and musculoskeletal conditions, all of which require diagnostic imaging for screening, diagnosis, and treatment monitoring. IBISWorld projects the US medical device industry revenue to grow at a 2.2% CAGR through 2030 on the back of these demographic dynamics alone, and that is a conservative, industry-wide figure that understates the growth for premium players like GEHC, who are gaining share through innovation. This should provide decades of volume growth for medical imaging and diagnostic platforms.
In addition to the tailwinds above, GEHC is also rebuilding its S-curve through its expansion into SaaS, which should drive consistent low-double-digit growth for the company for a long time. The acquisition of Intelerad should drive this transition and transform GEHC into a cashflow machine.
Headwinds
The healthcare machines market is cyclical because hospital spending is based on reimbursement, taxes, and government spending, but GEHC’s growing SaaS products should start to mitigate this.
Also, competition from Chinese players could prove to be a significant headwind, as GEHC’s performance in China has been soft lately. However, the “AI software startups will kill GEHC’s SaaS offerings” is lazy, in my opinion. GEHC owns the data from its machines, which means it can create a walled garden that chokes out competition and allows GEHC to pry its way into better deals and improve unit economics.
The Numbers
Diving right in, GEHC has a P/E of 16.5 and a forward P/E of 14.4. GEHC also trades for 13.7x EV/EBIT and 7.8x forward EV/EBIT. This valuation is significantly lower than its GE brethren on a trailing P/E basis (GE: 35 and GEV: 50), and I think this gap should close over time. Compared to peers, GEHC also appears cheap, as Siemens Healthineers trades at 18x, and Koninklijke Philips at 25x.
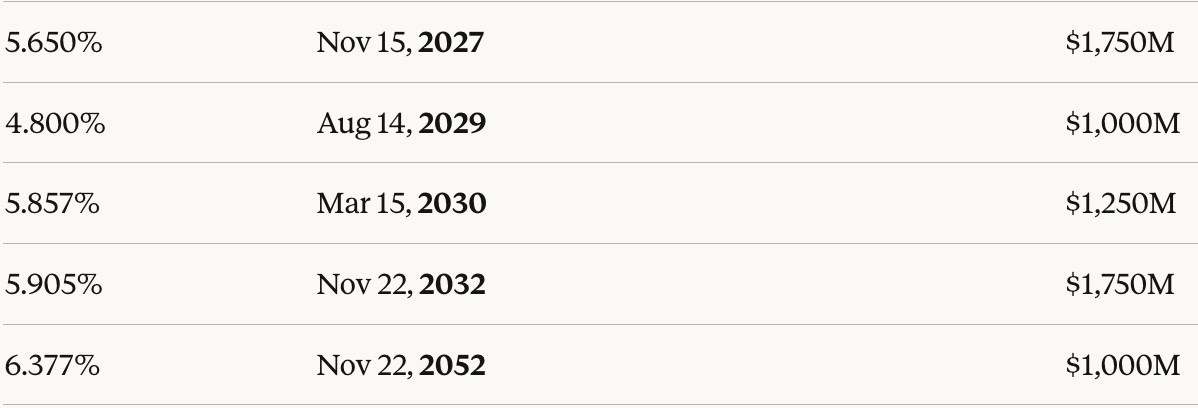
GEHC has about $4 billion in cash and equivalents right now, compared with $9.5 billion in long-term debt. However, most of this debt is from the GE spinoff, as GE passed $10 billion in senior notes and term loans to GEHC to clean up its own balance sheet. GEHC also assumed $5 billion in pension and other post-retirement obligations as part of the spinoff deal.
My projections for GEHC revenue growth are as follows: Products revenue growth of 5% and Services revenue growth of 15%. This would mean GEHC has a total 2031 revenue figure of about $31.5 billion (services still represent less than half of revenue, although the gap is far smaller). I also think margins will expand to about 17%, reflecting an uplift from the higher margins of Services. This means GEHC will generate $5.35 billion in 2031 operating income, representing a 7x EV/operating-income multiple. Assuming a 20-25x exit multiple, which I think is acceptable for a growing recurring revenue base, representing 3-4x upside.
*Disclaimer* You may disagree with my growth assumptions. These assumptions are not guaranteed, and I could be wildly off. Always do your own modeling with your own assumptions. Also, I do not factor in stock-based compensation, but I recommend that you consider it when doing your own modeling. Also acknowledge that if these assumptions don’t work out, the investment will likely result in a loss of capital.
The Pre-Mortem
This segment is me trying to pick apart why the stock would underperform over the next five years. I thought it meaningful to add this segment after reading some Charlie Munger quotes about truly understanding businesses. Munger once said that you don’t understand a stock unless you know why it won’t work (I am merely paraphrasing). Reason one: Chinese competition will eat away at GEHC’s margins and lead to a revenue growth stagnation. Reason two: Management fails to transition GEHC to services, meaning margins and revenue growth won’t be great. Reason three: GEHC makes bad acquisitions that destroy the somewhat fragile balance sheet and could potentially lead to bankruptcy.
The Thesis
Owning GEHC means you believe that Chinese competition won’t be that bad and that management can execute on making Services a larger part of revenue. Investors are well compensated for risk with the large potential upside (potentially 3-4x). If GEHC can only meet expectations, this is a great long-term compounder.
Happy investing, Cade
If you have any suggestions for a future write-up, please leave a comment or put it in the subscriber chat.
Please remember that I am not a financial advisor, and anything I say is not formal financial advice. I may buy, sell, or hold securities discussed and may plan to buy, sell, or hold them in the future.